 Oct, 26 2026
Medicare Part B Premium & Deduction Estimator
Enter your details below to estimate how much will be deducted from your Social Security check for Medicare Part B in 2026.
Estimated Results
Standard Part B Premium:
$185.00
IRMAA Surcharge:
+$0.00
Total Monthly Medicare Deduction:
$185.00
Net Social Security Deposit:
$0.00
Hold Harmless Rule: If you receive Social Security benefits, your premium increase is generally limited by the Cost-of-Living Adjustment (COLA). However, high earners paying IRMAA are exempt from this protection.
You check your bank account after a Social Security deposit hits, and the number is lower than you expected. It’s not a mistake, and it’s not inflation eating your lunch money alone. For most retirees, this gap is Medicare Part B the medical insurance portion of Medicare that covers doctor visits, outpatient care, and preventive services. If you get your benefits through the Social Security Administration (SSA), they handle this payment for you automatically. But how much do they actually take out? And why does the amount change?
The Standard Premium in 2026
Let’s cut to the chase. In 2026, the standard monthly premium for Medicare Part B is $185. This figure isn’t pulled from thin air; it’s adjusted annually based on national spending per beneficiary. If you’re a new enrollee or someone who hasn’t had significant income changes, this is likely what will be deducted from your Social Security check. However, this number is just the baseline. Your actual deduction could be higher, depending on your financial situation.
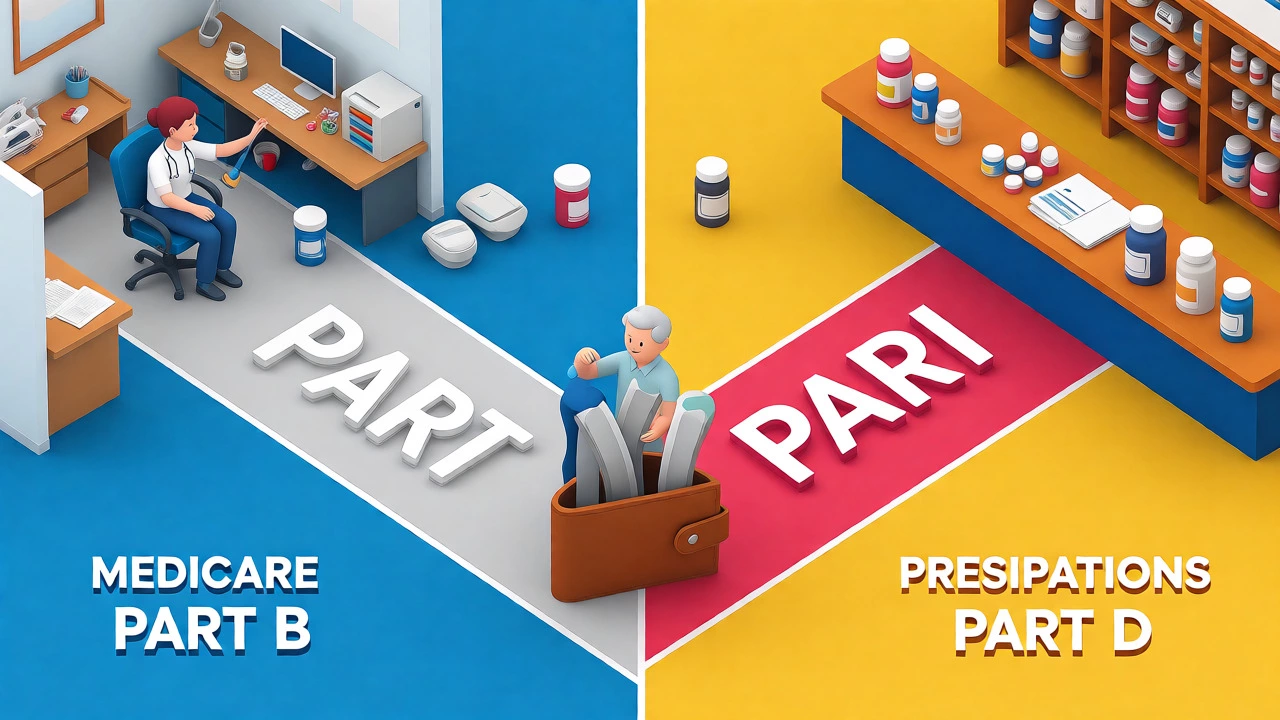
Why does the government deduct it directly? Convenience. By linking the payment to your Social Security benefit, the SSA ensures you don’t accidentally miss a payment and lose coverage. This process is known as "hold harmless" protection, but more on that later. First, you need to understand what this money buys you. Part B doesn’t cover everything. It handles doctor visits, ambulance services, durable medical equipment, and crucially, some medications administered by a doctor. It does not typically cover prescriptions you pick up at the pharmacy counter-that’s Part D territory. Confusing these two is the biggest mistake people make when budgeting for healthcare.
Who Pays More? The Income-Related Adjustment
Not everyone pays the flat $185 rate. If your modified adjusted gross income (MAGI) from two years prior exceeds certain thresholds, you pay an extra amount called IRMAA (Income-Related Monthly Adjustment Amount). Yes, the IRS looks back at your taxes from 2024 to determine your 2026 premiums. It feels like a time delay glitch, but it’s how the system works.
| Filing Status | Annual Income Threshold | Total Monthly Premium (Est.) |
|---|---|---|
| Single Filer | $97,000 or less | $185.00 |
| Single Filer | $97,001 - $123,000 | $259.20 |
| Single Filer | $123,001 - $153,000 | $370.30 |
| Married Jointly | $194,000 or less | $185.00 |
| Married Jointly | $194,001 - $246,000 | $259.20 |
These numbers are estimates based on recent trends, as exact 2026 brackets can shift slightly with inflation adjustments. If you sold a house or cashed out a large retirement account in 2024, your 2026 bill might jump significantly. You’ll receive a letter from the SSA if this happens. Don’t ignore it. You can appeal if the income spike was a one-time event, like selling a business or inheriting a lump sum.
The Hold Harmless Rule: Your Safety Net
Here is a critical piece of information that saves many seniors from a nasty surprise. The "Hold Harmless" provision limits how much your Social Security check can drop due to premium increases. Generally, your Part B premium cannot increase by more than the cost-of-living adjustment (COLA) applied to your Social Security benefits. If premiums skyrocket while your COLA is low, your deduction stays capped at the previous year’s level plus the COLA amount.
However, there are exceptions. If you’re a high earner paying IRMAA, if you enrolled late, or if you’re not receiving Social Security benefits yet, hold harmless doesn’t apply to you. In those cases, you pay the full current-year premium. This distinction matters because it affects your net income. A sudden $50 jump in premiums when you only got a $30 raise means you effectively took a pay cut.
Part B vs. Part D: Where Do Prescriptions Fit In?
Since this topic often intersects with prescription costs, let’s clarify the split. Medicare Part B covers drugs you receive during a visit-think chemotherapy infusions, flu shots, or injectables given in a clinic. These costs are subject to the Part B deductible and coinsurance, but the premium itself doesn’t change based on how many shots you get.
Your daily pills, however, fall under Medicare Part D optional prescription drug plans offered by private companies approved by Medicare. Part D premiums vary wildly between plans. Some are $10, others are $100+. Unlike Part B, which is mandatory if you want comprehensive coverage, Part D is optional-but skipping it can lead to lifetime penalties if you join later. When you look at your Social Security deduction, you might see two lines: one for Part B and another for Part D if you chose to have it deducted automatically. Combining them gives you the true picture of your healthcare overhead.
How to Check and Manage Your Deduction
You shouldn’t have to guess what’s being taken out. Here is a simple checklist to verify your deductions:
- Review your Award Letter: When you first started benefits, the SSA sent a letter detailing your gross monthly benefit and any deductions.
- Check Your Bank Statement: Look for line items labeled "MEDICARE PART B" or similar codes. Note the exact date and amount.
- Log into My Social Security: Create an account on ssa.gov. The "Payment History" section shows exactly how much was withheld each month.
- Watch for Annual Notices: Every fall, Medicare sends a "Notice of Change" outlining next year’s premiums. Compare this to your current deduction.
If you find errors, contact the SSA immediately. Sometimes, overpayments occur if you switched plans mid-year or if you paid Part B separately via mail while also having it deducted from Social Security. Double-dipping leads to refunds, but it takes months to resolve. Keep records of all payments made outside the automatic deduction.
Strategies to Lower Your Out-of-Pocket Costs
Can you reduce this deduction? Not directly, since the premium is set by the federal government. But you can manage the impact on your wallet. If you’re still working, consider contributing to a Health Savings Account (HSA) if eligible, though this is rare for those already on Medicare. For most, the strategy lies in choosing the right supplemental coverage.
Many people buy Medigap (Medicare Supplement Insurance) policies. These private policies help pay for copays and deductibles that Part B doesn’t cover. While Medigap has its own premium, it can stabilize your annual healthcare spending. Alternatively, Medicare Advantage Plans (Part C) bundle Part B and often Part D into one plan, sometimes with lower out-of-pocket maximums. Compare these options carefully. A lower Part B deduction doesn’t mean better overall value if you’re paying huge copays for every doctor visit.
Remember, healthcare costs are rising faster than general inflation. Budgeting for the standard $185 is smart, but planning for potential IRMAA hikes is smarter. If you anticipate an income spike, consult a tax advisor before making large financial moves in the year that will be reviewed two years later.
Does everyone get Medicare Part B deducted from Social Security?
No. Only those who receive Social Security benefits and are enrolled in Part B have it deducted automatically. If you receive Railroad Retirement Board benefits or Civil Service Retirement System benefits, the rules may differ slightly, but direct deduction is common. If you don’t receive Social Security, you must pay the premium directly to Medicare via bill.
What happens if my Social Security check is smaller than the Medicare premium?
This is rare but possible if you have very low benefits and high IRMAA surcharges. In such cases, the SSA will usually withhold the entire check until the debt is covered, or send you a bill for the remainder. It’s crucial to communicate with the SSA to avoid service interruptions.
Can I opt out of having Medicare Part B deducted from Social Security?
Yes, you can request to pay Medicare directly instead of having it deducted from your Social Security check. This requires filing Form CMS-1763. People sometimes do this to manage cash flow or if they prefer paying via credit card for points/rewards, though Medicare accepts checks and electronic transfers too.
Why did my Medicare deduction go up so much this year?
Two main reasons cause spikes: general premium increases due to inflation, or an IRMAA surcharge triggered by higher income reported on your tax return from two years ago. Check your tax return from two years prior to see if your MAGI crossed a threshold.
Is the Medicare Part B premium tax-deductible?
Generally, no. Because the premium is deducted pre-tax from Social Security benefits (which are often partially taxable), you cannot claim it as an additional medical expense deduction on your federal tax return unless you itemize deductions and your total medical expenses exceed 7.5% of your adjusted gross income.
